What Home Insurance May Cover
For a West Jordan homeowner, insurance may cover water damage from a burst line when the event fits the policy, while payment to fix the pipe itself may be treated separately. That distinction is central to burst pipe repair insurance: damage to the home and the failed plumbing can fall under different terms. The contract and the cause of the break matter, so do not assume the pipe repair is covered simply because water damage may qualify.
A wet area alone does not establish whether a break was sudden or developed over time. If you live near the Jordan River or elsewhere in West Jordan, avoid guessing at the cause based on the season or where the water appeared. Ask your insurer how it evaluates the cause and the pipe work before you rely on plumbing claim coverage or agree to a permanent repair.
Separate Pipe Work From Water Damage
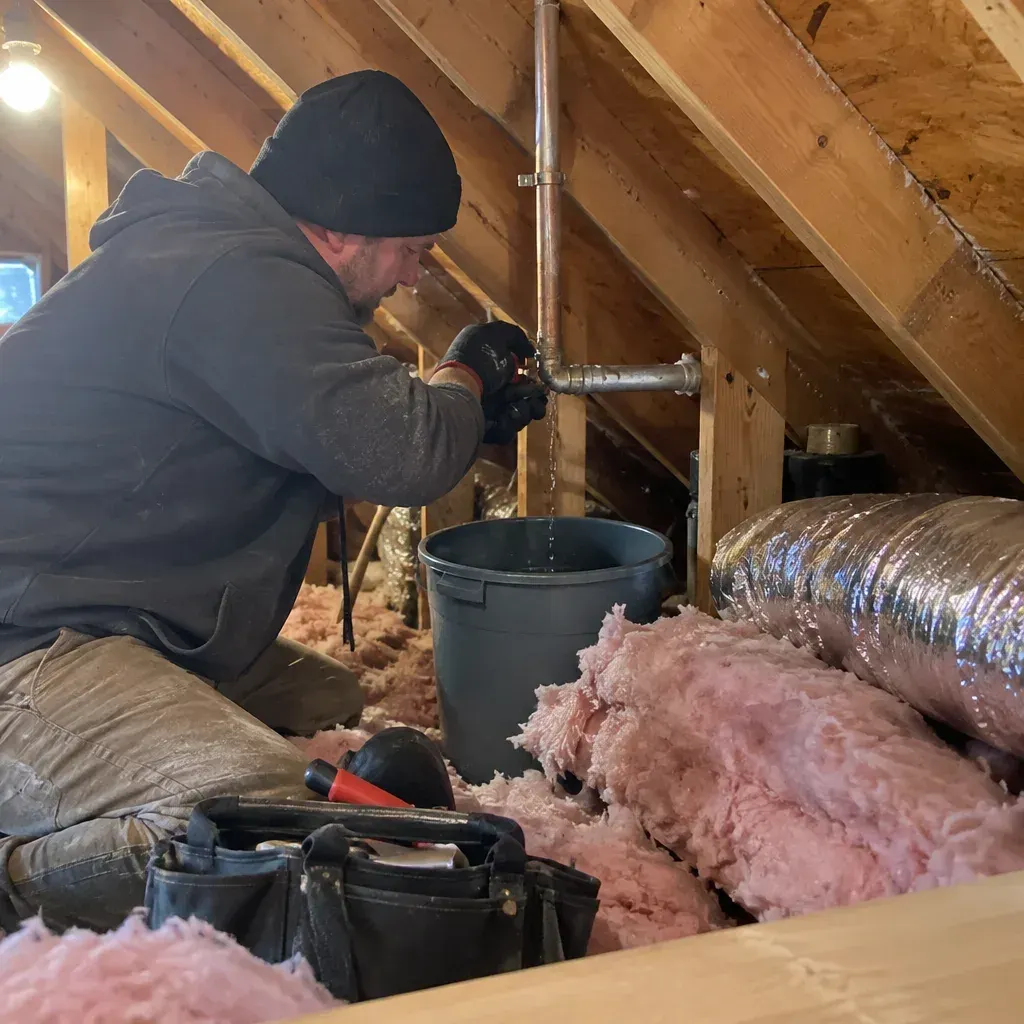
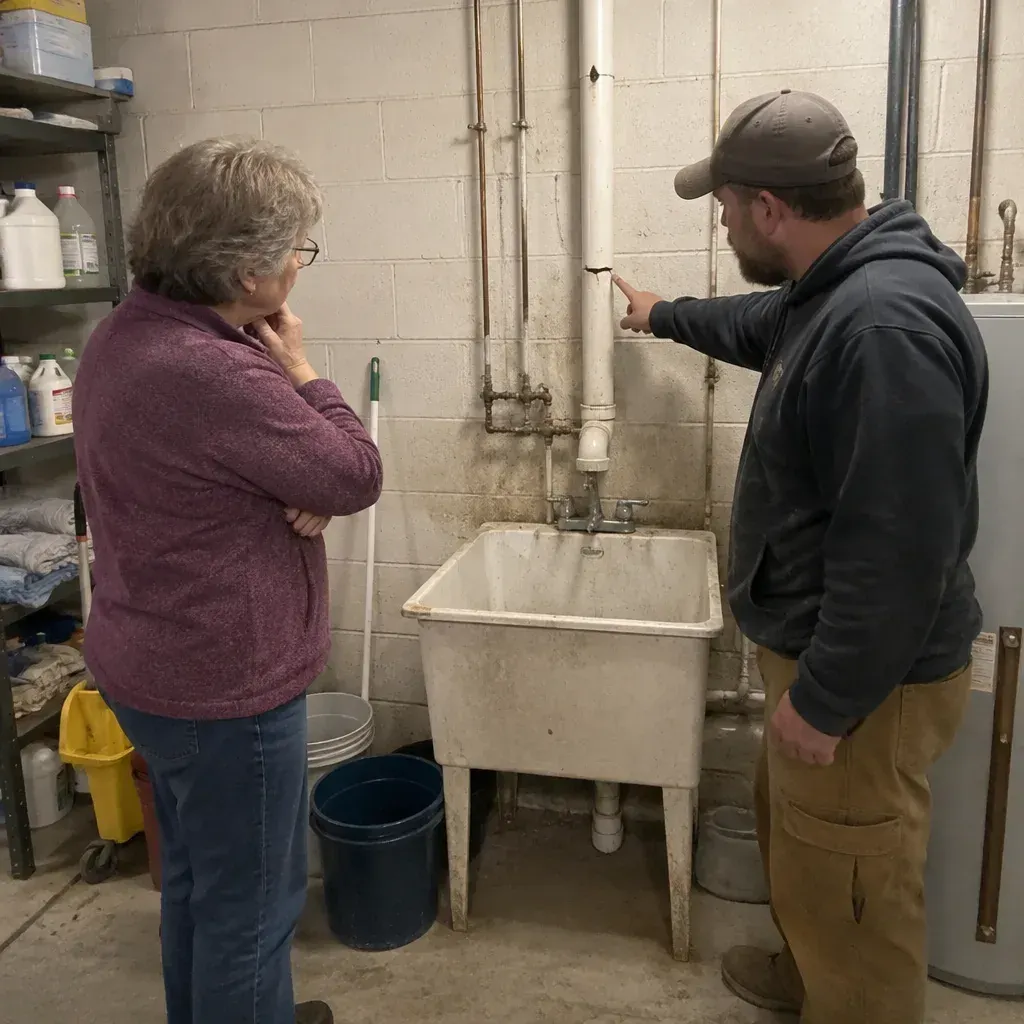
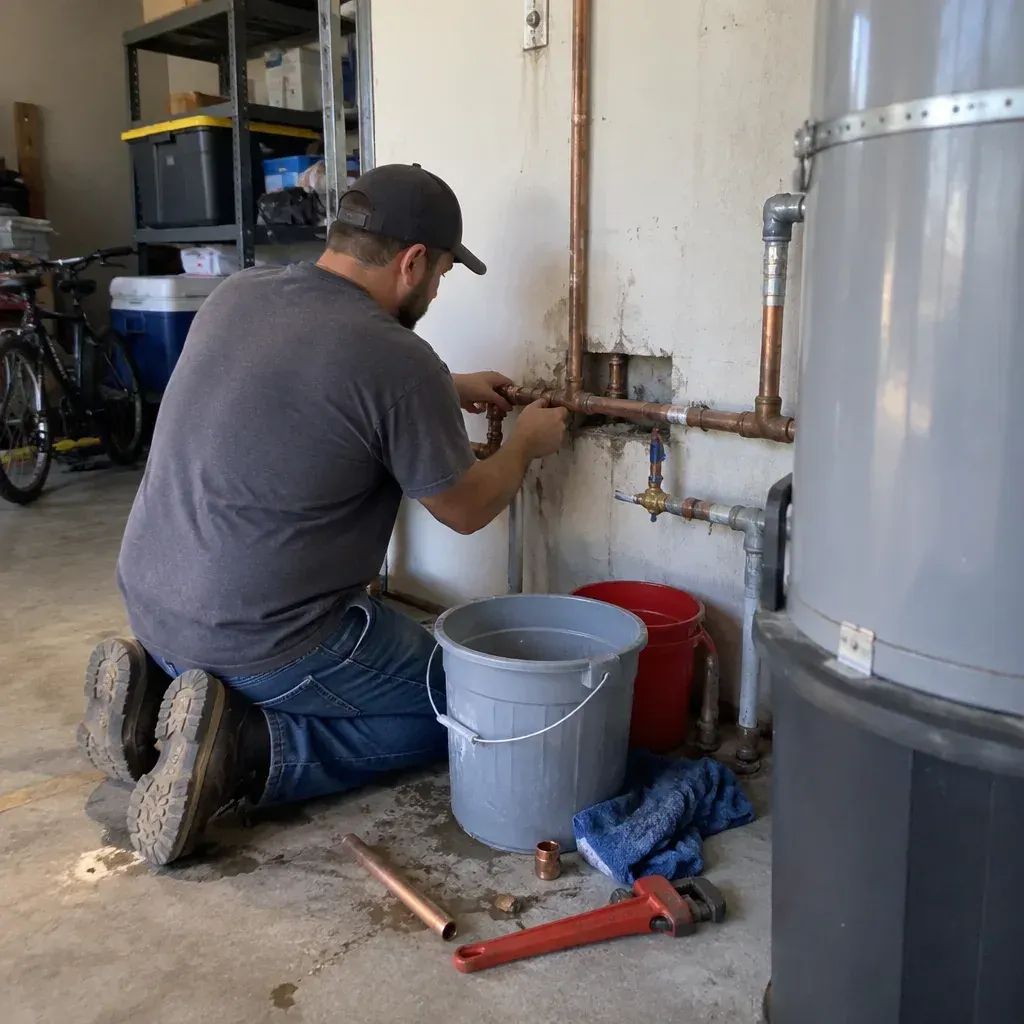
Separate the failed line from the damage it caused when you ask about home insurance pipe repair. A plumber's description may identify the damaged section and the work needed to restore the water line, while your policy may address resulting damage under different wording. Ask the insurer to explain which part of the claimed work it considers eligible, since approval for damage to the home does not automatically settle payment for the plumbing repair.
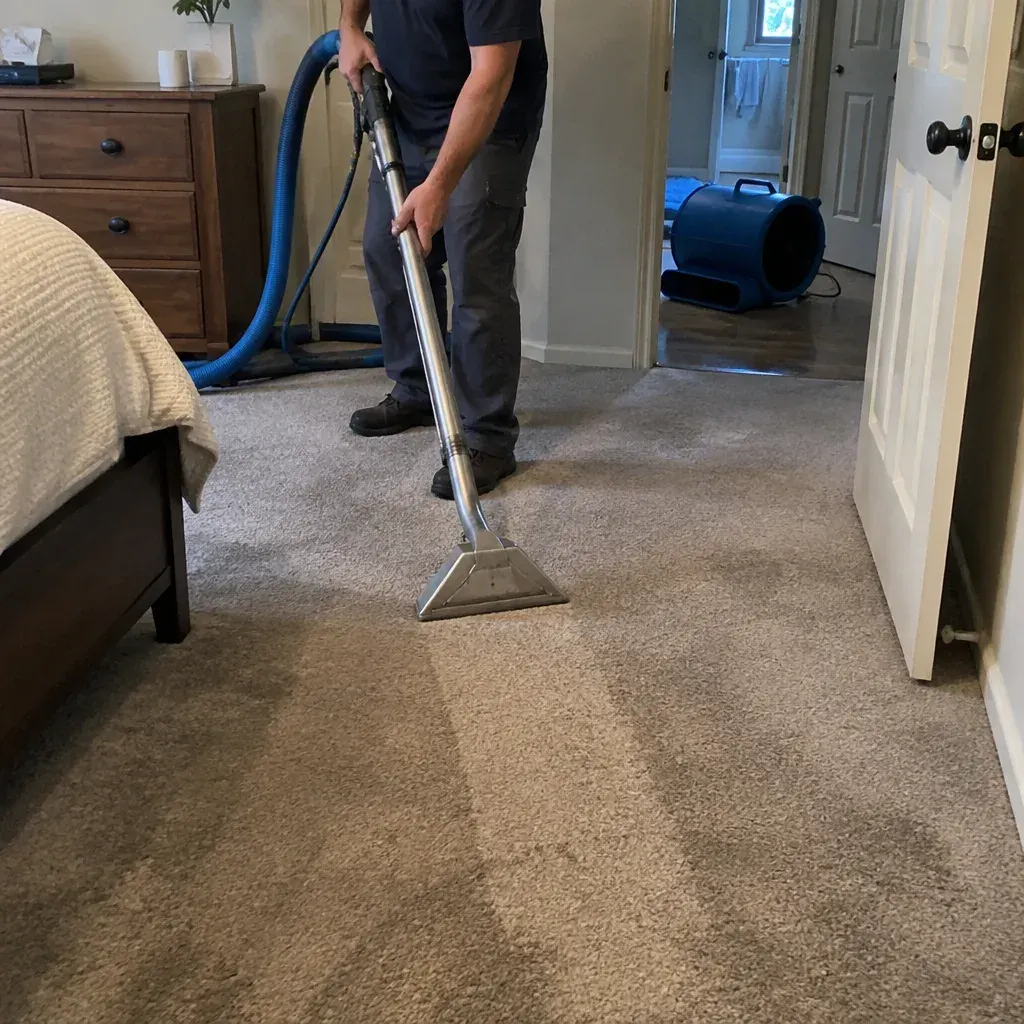
Do not postpone a safe water shutoff while waiting for an insurance answer; continued flow can worsen the loss. Water can also seep beneath flooring and into wall cavities, leaving hidden materials damp after the visible leak stops. Whether your home is near Veterans Memorial Park or elsewhere in West Jordan, contact the insurer promptly and ask whether it wants to inspect the affected pipe before permanent work proceeds.
How Policy Terms Affect Coverage
Read the exclusions and conditions that address wear, maintenance, and gradual leakage, because they can change how a claim is assessed. Policy wording may distinguish a break that happens abruptly from damage tied to an ongoing condition. A homeowner near Bingham Creek should not infer coverage from the location or the visible damage; check the actual contract and ask the insurer which provision applies to the reported cause.
The suspected source can matter as much as the visible result. If the plumber finds a split supply line, the insurer may assess that explanation differently from a leak linked to a fitting or another plumbing component. In West Jordan, ask what information the insurer needs to understand the cause, and whether its view could change if the inspection points to a condition that existed before the water release.
Deductibles and Your Next Steps
A deductible affects what you may receive after the insurer decides a loss qualifies; it does not establish eligibility by itself. Before choosing whether to file, ask how the deductible applies to the covered portion and whether the pipe repair is being considered separately. That can help you avoid treating an initial estimate of damage as a promise of payment for every part of the work.
After the water is controlled, call your insurer and describe the event plainly, then ask what it wants you to do before authorizing permanent repairs. Follow any instructions about access or inspection while keeping the line from causing further damage when it is safe to do so. For a West Jordan home, confirming the insurer's process early can prevent a coverage dispute from delaying the next decision.
Dealing with a burst pipe in your home?
A musty odor or bubbling paint can signal trapped moisture even when the pipe itself is out of sight. Move nearby belongings away from damp surfaces when safe to help limit water damage. When calling the pros we connect you with, ask whether they can take the job, when a visit might fit, and whether a visit charge applies. For directions, Hale Centre Theatre, Decker Lake, or Copperton Historic District can help clarify a route. Pipe repair addresses the line; extraction and drying may require another provider.